The Hidden Price of Switching Pharmacies: What Transferring Your Prescriptions Actually Costs You
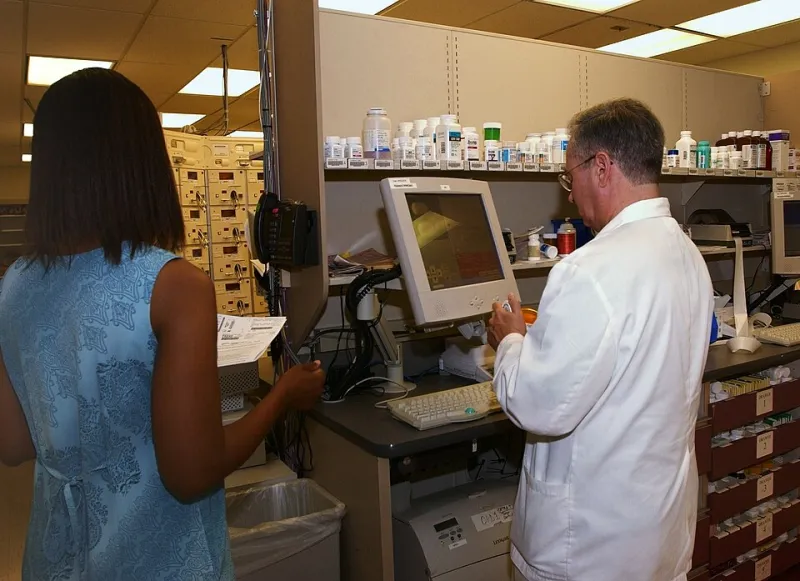
Photo: U.S. Navy photo by Chief Warrant Officer 4 Seth Rossman., Public domain, via Wikimedia Commons
Switching pharmacies feels like a straightforward consumer decision. You find a better price, a more convenient location, or a friendlier service model, and you ask for your prescription to be moved. What most patients do not realize is that this routine act can trigger a cascade of financial consequences that erode — or entirely eliminate — any savings that motivated the transfer in the first place.
At Rx Price Watch, we track the mechanisms behind prescription pricing so consumers can make genuinely informed decisions. The pharmacy transfer process is one of the least transparent areas of retail drug purchasing, and the costs embedded within it deserve serious scrutiny.
What Happens Behind the Counter When You Request a Transfer
When a patient requests a prescription transfer, the receiving pharmacy must contact the original dispenser to obtain a valid prescription record. For controlled substances, federal law prohibits outright transfers in most circumstances, which immediately limits patient flexibility for a significant category of medications. For non-controlled drugs, the process is theoretically simple — but in practice, delays, system incompatibilities, and administrative friction frequently create gaps in dispensing that cost patients money.
Those gaps matter for a specific reason: insurance adjudication timing. Many pharmacy benefit managers (PBMs) — the intermediaries that process drug claims on behalf of insurers — assign fill windows and refill eligibility dates to individual pharmacy locations, not to the patient's account universally. When a prescription moves to a new pharmacy, the receiving system sometimes cannot immediately access the prior fill history in a way the PBM recognizes. This can cause the insurance system to treat the transfer fill as an early refill, triggering a rejection or forcing the patient to pay out of pocket until the eligibility window catches up.
The Deductible Displacement Problem
Perhaps the most financially damaging consequence of a mid-year pharmacy transfer is what might be called deductible displacement. Many insurance plans track spending accumulation — the amount credited toward your annual deductible or out-of-pocket maximum — at the claim level, tied to specific dispensing records. When a transfer occurs and the new pharmacy files a claim that the PBM cannot immediately reconcile with prior payments, some patients find that recent spending history does not carry forward correctly in the short term.
This does not mean your deductible progress is permanently lost. It does mean that for one or more fill cycles, you may be charged as though you are starting fresh — paying the full contracted rate rather than the post-deductible copay you had earned. For patients managing expensive chronic medications, this temporary misalignment can cost $100 to $400 or more on a single fill.
Chain Pharmacies and the Architecture of Transfer Friction
Not all pharmacy systems treat transfers the same way. Large national chains have a documented financial incentive to retain customers, and some have engineered their internal systems to make departures more cumbersome than arrivals. Tactics vary, but commonly include:
- Delayed record release. Some pharmacies are slow to transmit records to competitors, occasionally requiring patients to wait 24 to 48 hours for a transfer that could theoretically be completed in minutes.
- Partial record transmission. Sending prescription information without complete fill history, which can confuse PBM systems and cause adjudication errors at the receiving pharmacy.
- Loyalty program entanglement. Discount pricing tied to store membership programs may expire or reset upon transfer, meaning the price you were quoted at the new pharmacy assumes a discount you no longer qualify for once your loyalty account status is evaluated.
Independent pharmacies and smaller regional chains tend to have fewer systemic incentives to obstruct outgoing transfers, though their system infrastructure may introduce its own compatibility challenges when interfacing with major PBM networks.
When Insurance Plans Penalize the Move
Some employer-sponsored health plans include provisions that financially favor specific pharmacy networks. Preferred pharmacy arrangements — often negotiated between plan sponsors and PBMs — offer lower copays at designated dispensing locations. Transferring outside of that preferred network, even to another major retailer, can shift a patient from a preferred tier copay to a non-preferred tier, sometimes doubling or tripling the per-fill cost.
Patients are frequently unaware of these network distinctions because plan documents describe them in technical language buried deep in the Summary of Benefits. The practical result is that a transfer made to capture a $15 savings on a 30-day supply can instead trigger a $40 copay increase that persists for every fill thereafter — until the patient either transfers back or selects a preferred pharmacy.
Before initiating any transfer, it is worth calling the member services number on your insurance card and asking two direct questions: Is the pharmacy I am transferring to in my plan's preferred network? And will transferring affect my current copay tier?
Strategies for Transferring Without Triggering Unexpected Costs
The good news is that most transfer-related costs are avoidable with deliberate planning. The following strategies significantly reduce the financial risk of moving prescriptions:
Time transfers to natural refill boundaries. Rather than transferring mid-cycle, wait until your current supply is nearly exhausted and your next fill is due. This eliminates the early refill complication and gives insurance systems a clean adjudication window at the new location.
Request complete fill history documentation. Before leaving your current pharmacy, ask for a printed or digital record of your fill history, including fill dates, quantities dispensed, and the prescribing physician's information. Providing this directly to the receiving pharmacy can prevent gaps caused by incomplete record transmission.
Verify network status before committing. Confirm preferred network status with your insurer before the transfer, not after. A five-minute phone call can prevent months of elevated copays.
Use price comparison tools at the destination pharmacy. Prices at the receiving pharmacy should be verified using current GoodRx, RxSaver, or similar tools before the transfer is finalized. Quoted prices at the time of transfer inquiry can differ from actual prices at the time of dispensing, particularly if a coupon rate has changed.
Transfer at the start of a plan year. If a transfer is planned, the beginning of the calendar year — when deductibles reset for everyone — is the cleanest time to execute the move. Your accumulation history starts fresh regardless, which removes the deductible displacement risk entirely.
The Cost of Staying Put vs. The Cost of Moving
This publication has previously documented the financial cost of pharmacy inertia — the tendency to remain at a familiar pharmacy despite better pricing elsewhere. That cost is real. But the cost of a poorly executed transfer is equally real, and for some patients in some plan structures, it exceeds the savings that motivated the move.
The answer is not to avoid transfers categorically. It is to approach them with the same analytical rigor you would apply to any significant financial decision. Know your plan's network structure. Understand your PBM's adjudication behavior. Time your move strategically. And verify pricing at the destination before your prescription record arrives.
Pharmacy transfers, handled correctly, can be a powerful tool for reducing annual prescription costs. Handled carelessly, they become one more mechanism through which the complexity of the US drug pricing system extracts money from patients who simply wanted a better deal.